True-Up Payments and Working Capital in M&A
True-up payments in M&A help ensure that buyers receive the agreed level of net working capital at closing. They also protect sellers when actual working capital exceeds the negotiated target.
Most M&A transactions value a company as a going concern. Accordingly, the purchase price generally assumes the seller will deliver sufficient working capital to support normal operations. Buyers should not need to contribute additional capital immediately after closing simply because working capital was depleted before the transaction.
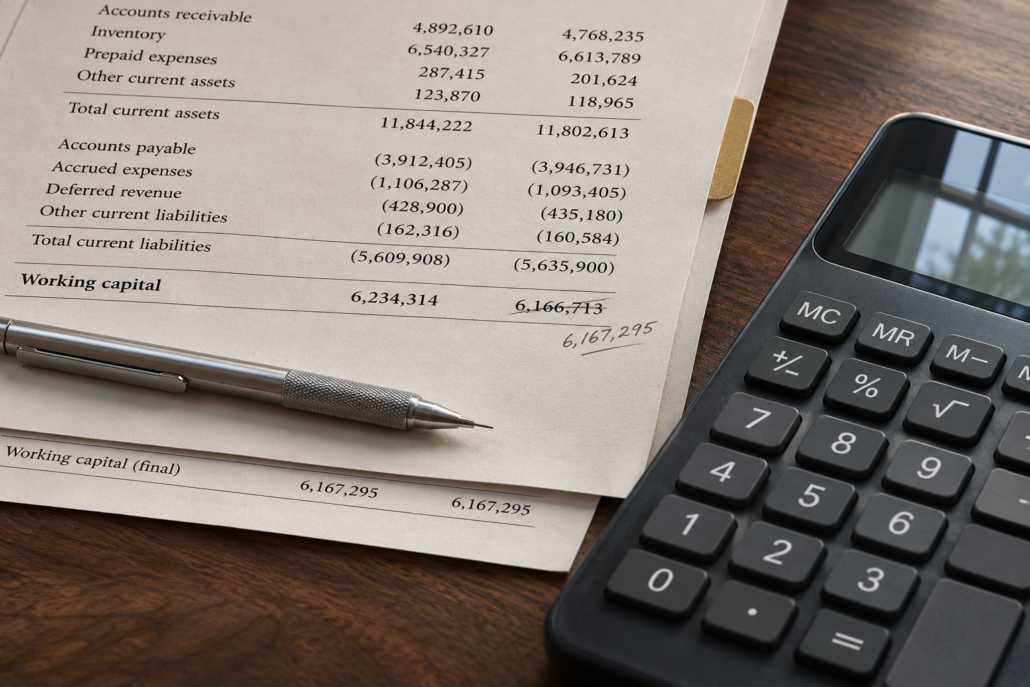
However, working capital changes continuously as a company operates. Accounts receivable, inventory, accounts payable, accrued expenses, and other current accounts may fluctuate significantly before closing. Therefore, buyers and sellers typically establish a targeted net working capital amount before completing the transaction.
At closing, the parties compare actual net working capital with the agreed target. If actual working capital falls below the target, the purchase price generally decreases by the shortfall. Conversely, the seller generally receives additional consideration when actual working capital exceeds the target.
For example, assume the parties establish a $1.0 million working capital target. If closing working capital equals $900,000, the purchase price could decrease by $100,000. If closing working capital equals $1.1 million, the seller could receive an additional $100,000.
Although the concept appears straightforward, the calculation may become contentious. Buyers and sellers may disagree about account classifications, accounting policies, reserves, accruals, or unusual balances. Furthermore, the parties may calculate certain accounts differently after closing.
For these reasons, sellers should address true-up payments in M&A during the Letter of Intent negotiations. The parties should clearly define working capital, the target amount, calculation methodology, and applicable accounting principles. They should also establish procedures for resolving disagreements.
Addressing these matters early provides several benefits:
- Reduces uncertainty surrounding the final purchase price
- Establishes consistent expectations before closing
- Limits disagreements over accounting classifications and methodologies
- Reduces opportunities to use working capital adjustments as a renegotiation tool
- Provides a defined process for resolving post-closing differences
An experienced M&A advisor may help sellers understand working capital targets and evaluate proposed adjustment mechanisms. Careful negotiation before closing reduces surprises and helps preserve the economics negotiated between buyer and seller.