Understanding EBITDA in M&A Transactions
Earnings Before Interest, Taxes, Depreciation, and Amortization, or EBITDA, is a widely used measure of a company’s operating performance. Understanding EBITDA in M&A is particularly important because buyers and sellers frequently use it when evaluating earnings and enterprise value.
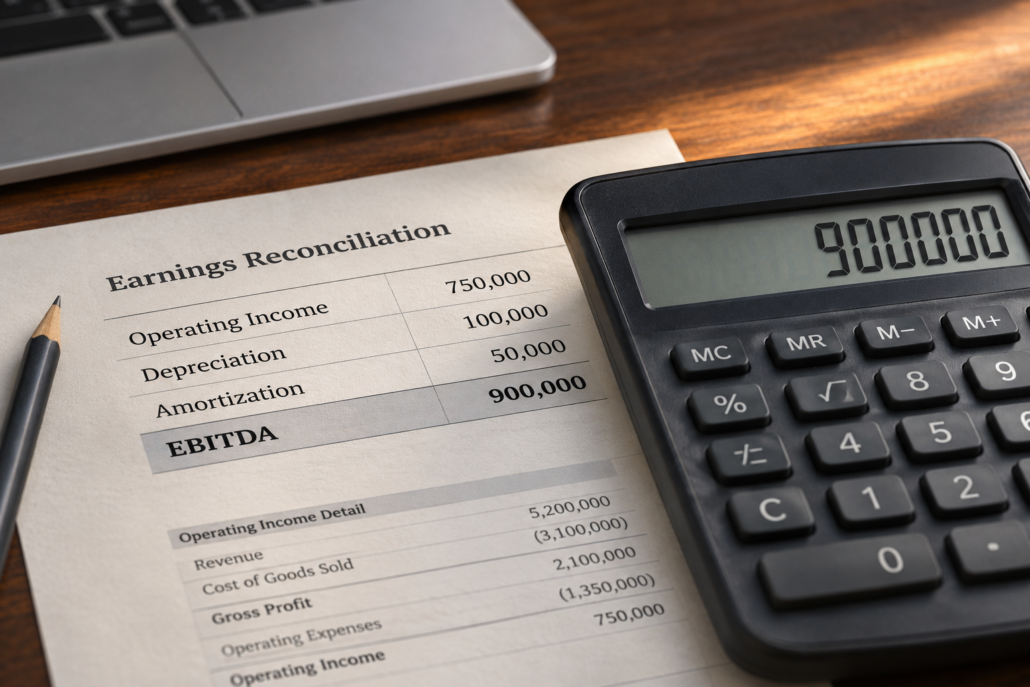
EBITDA begins with net income and adds back interest, income taxes, depreciation, and amortization. Removing interest helps buyers compare companies without considering differences in financing structures. Likewise, excluding income taxes reduces differences resulting from tax structures and other tax-related factors. Depreciation and amortization represent non-cash expenses recorded on the income statement. Therefore, adding these expenses back provides another perspective on operating profitability before certain accounting charges.
The basic formula is:
EBITDA = Net Income + Interest Expense + Income Taxes + Depreciation + Amortization
The analysis of EBITDA in M&A often extends beyond the amount reported in a company’s financial statements. M&A advisors analyze historical earnings and identify legitimate adjustments that better represent the company’s ongoing financial performance. These adjustments may include unusual, nonrecurring, or discretionary expenses that will not continue under new ownership.
For example, adjustments might address excess owner compensation, personal expenses, unusual professional fees, or one-time operating costs. However, buyers carefully scrutinize these adjustments during due diligence. Accordingly, sellers should maintain supporting documentation for every proposed adjustment.
EBITDA also plays an important role in valuation because buyers frequently apply valuation multiples to normalized EBITDA. However, EBITDA should never serve as the only measure of financial performance. It does not account for capital expenditures, working capital requirements, debt payments, or changes in cash balances. As a result, EBITDA does not equal cash flow.
Charlie Munger famously criticized EBITDA because he believed it could obscure important economic costs. His criticism highlights an important point for business owners. EBITDA provides useful information, but investors must evaluate it within the broader financial and operational context of the business.
Understanding EBITDA in M&A requires recognizing both its usefulness and limitations. Buyers and sellers should consider EBITDA alongside cash flow, growth prospects, capital requirements, working capital, and other financial considerations. An experienced M&A advisor will help analyze these factors and determine how they affect a company’s financial performance and potential value.