How to Compare Competing M&A Offers
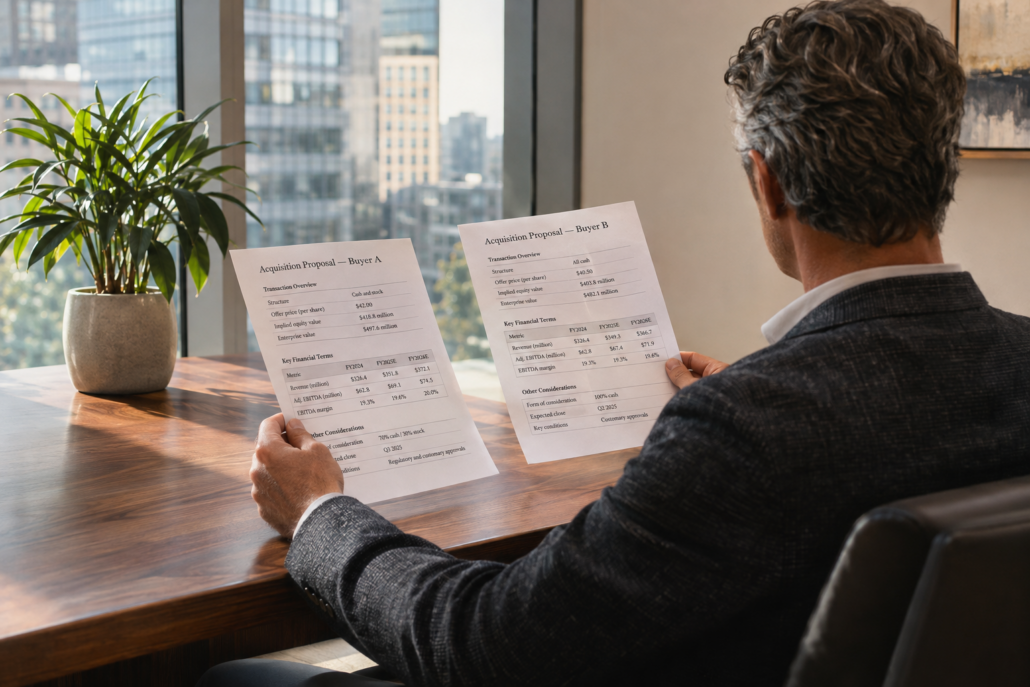
Business owners receiving multiple offers may naturally focus on the highest purchase price. However, headline price tells only part of the story. Two buyers may offer the same purchase price while providing significantly different economic outcomes. Therefore, comparing M&A offers requires evaluating both price and transaction structure.
The analysis should begin with the consideration each buyer proposes. Cash at closing generally provides the seller with the greatest certainty and immediate liquidity. However, many transactions include other forms of consideration. These may include seller notes, earnouts, buyer stock, rollover equity, or deferred payments. Each form carries different risks and potential rewards. A $2 million seller note, for example, does not equal $2 million cash at closing. The seller must wait for payment and assume the buyer’s credit risk. Additionally, the note’s interest rate, maturity, collateral, and payment terms affect its value.
Earnouts require similar analysis because payment depends on future performance. Sellers should evaluate the performance requirements, measurement period, payment terms, and their ability to influence results. Rollover equity presents a different tradeoff. The seller gives up current liquidity in exchange for continued ownership and potential future appreciation. Buyer stock may also create uncertainty. Its value depends on the buyer’s financial performance, liquidity, transfer restrictions, and other investment considerations.
Beyond consideration, sellers must examine adjustments that affect actual proceeds. Working capital requirements, assumed debt, transaction expenses, and other obligations may materially change cash received at closing.
Escrows and indemnification holdbacks may further reduce immediate proceeds. Although these amounts remain part of the transaction consideration, the seller may not receive them for months or even years.
Tax consequences also deserve careful consideration. Different transaction structures and forms of consideration may produce substantially different after-tax proceeds.
Once these factors are understood, the seller can compare each offer on a cash-equivalent basis. This analysis considers the timing, liquidity, risk, and probability of receiving each payment. For instance, a lower-priced offer with substantial cash at closing may outperform a higher offer containing significant contingent consideration. Conversely, rollover equity may make another offer attractive when the seller wants continued participation.
An experienced M&A advisor will help owners evaluate these differences and identify the tradeoffs within each proposal. Legal and tax advisors should also evaluate contractual protections and after-tax consequences.
A competitive sale process gives sellers the opportunity to compare more than purchase prices. It allows them to evaluate price, structure, certainty, timing, and risk across multiple buyers. Comparing M&A offers requires looking beyond the headline number. The strongest offer is the one that best balances economic value, certainty, and the seller’s transaction objectives.