Using Earnouts to Bridge Valuation Gaps in M&A
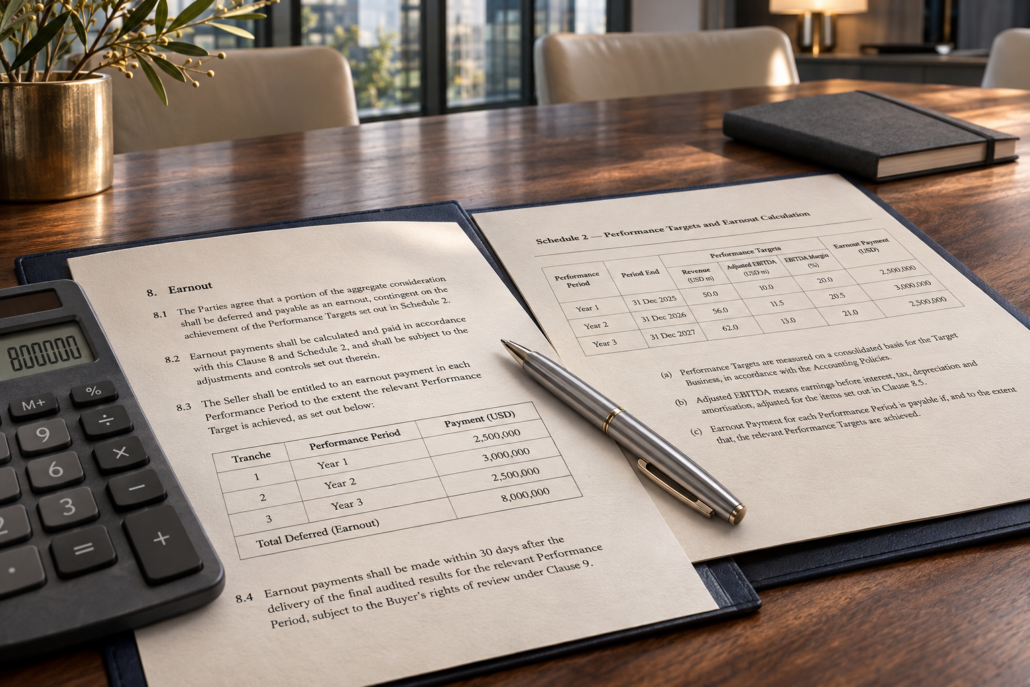
Earnouts in M&A may bridge valuation gaps when buyers and sellers disagree about a company’s future financial performance. However, these arrangements require careful negotiation because they introduce complexity and post-closing risk. An earnout makes a portion of the purchase consideration contingent upon the business achieving specified results after closing. Typically, the parties base those payments on revenue, EBITDA, customer retention, or another measurable performance metric.
Sellers often approach earnouts cautiously, and for good reason. Cash received at closing provides certainty, while an earnout represents contingent consideration. Furthermore, sellers may lose control over business decisions that directly affect their ability to achieve future payments. Nevertheless, earnouts remain useful when buyers and sellers hold different views about value. A seller may expect significant growth based on new customers, contracts, products, or other opportunities. Meanwhile, the buyer may hesitate to pay today for financial performance that has not yet occurred.
In these situations, earnouts in M&A may provide a practical compromise. The buyer pays additional consideration if the expected performance materializes. At the same time, the seller receives an opportunity to participate in the value created by that performance. Properly structured earnouts may serve several purposes:
- Bridge valuation differences: Connect additional consideration to future financial or operational performance.
- Provide measurable incentives: Encourage sellers or management teams to achieve agreed post-closing objectives.
- Support employee retention: Tie certain payments to the continued involvement of important employees when appropriate.
- Address uncertainty: Allocate risk when future contracts, customers, or growth opportunities remain uncertain.
- Align interests: Establish common objectives for buyers and sellers during the post-closing transition.
Still, the parties must define the earnout carefully. They should establish performance measurements, accounting policies, payment periods, calculation procedures, and dispute resolution mechanisms. Equally important, sellers should understand how the buyer will operate the company during the earnout period. Decisions involving expenses, investments, staffing, pricing, or acquisitions may materially affect performance. For this reason, sellers should never view an earnout as equivalent to cash at closing. Instead, they should evaluate its potential value alongside the probability of actually receiving payment.
An experienced M&A advisor will help sellers evaluate and negotiate earnouts in M&A before accepting an offer. When structured properly, an earnout may overcome uncertainty, align interests, and help bridge a valuation gap that might otherwise prevent closing.