Evaluating Purchase Consideration in an M&A Transaction
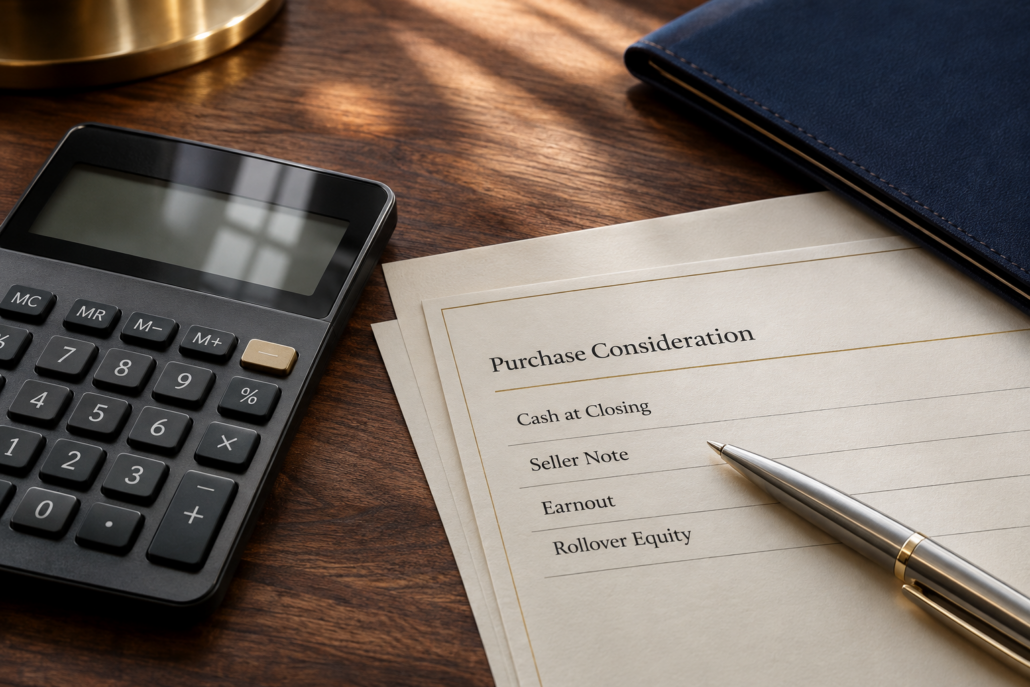
Sellers of lower middle market companies should evaluate more than the headline purchase price when comparing offers. Purchase consideration may include cash, seller financing, earnouts, rollover equity, escrows, holdbacks, and other forms of deferred payment. Consequently, two offers with identical purchase prices may provide significantly different economic outcomes for the seller.
Cash paid at closing generally provides the greatest certainty and immediate liquidity. However, buyers may use other forms of consideration to bridge valuation differences or address transaction risks. Sellers must therefore evaluate each component based on its economic value rather than its stated amount.
Two important considerations are the time value of money and the probability of collection.
The time value of money recognizes that one dollar received today exceeds the value of one dollar received later. Accordingly, sellers should discount future payments to determine their present value. Interest rates, payment periods, timing, and other financial assumptions affect that calculation.
The probability of collection introduces another important consideration. A contractual right to future payment does not necessarily provide the same certainty as cash at closing. Several factors may increase the risk associated with deferred or contingent payments:
- Seller financing exposes the seller to the buyer’s future ability to repay the obligation.
- Earnouts depend on achieving specifically defined financial or operational performance targets.
- Escrows and holdbacks may remain subject to indemnification claims or other post-closing adjustments.
- Rollover equity provides future upside potential but also exposes the seller to continued investment risk.
Earnouts deserve particular attention when evaluating purchase consideration. Poorly defined performance measurements may create disagreements between buyers and sellers after closing. Furthermore, the buyer may control operating decisions that directly influence whether the seller achieves the earnout. Therefore, sellers should compare offers using estimated cash equivalencies rather than headline purchase prices alone. A lower offer with greater cash at closing may provide more economic value than a larger contingent offer. Transaction structure, tax considerations, risk allocation, and the seller’s personal objectives may also influence the decision.
An experienced M&A advisor will help sellers evaluate competing offers and understand the economics behind each structure. Ultimately, the best offer balances purchase price, certainty of payment, transaction terms, and the seller’s objectives. Purchase consideration should always be evaluated based on what the seller reasonably expects to receive, not simply the number presented.