Why Financial Reporting Matters in M&A
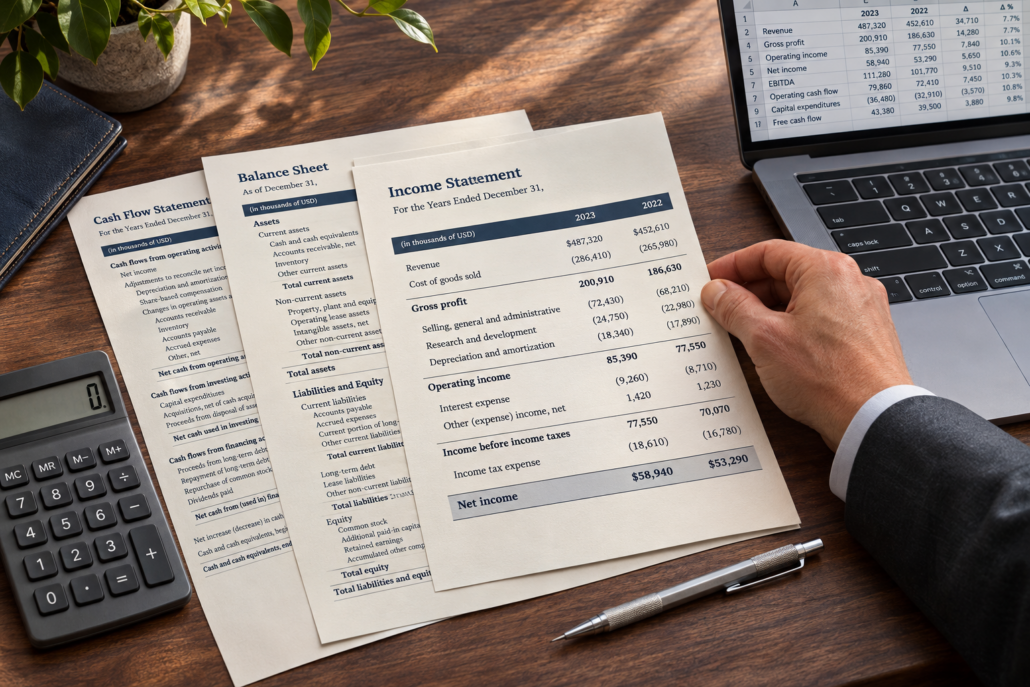
Reliable financial information plays a critical role in the sale of a lower middle market business. GAAP financial statements in M&A provide buyers with a consistent framework for evaluating historical financial performance. Generally Accepted Accounting Principles, or GAAP, establish recognized accounting standards for financial reporting in the United States. The Financial Accounting Standards Board maintains these standards through the FASB Accounting Standards Codification.
GAAP establishes principles governing revenue recognition, expenses, assets, liabilities, and numerous other accounting matters. Consequently, consistent application helps users compare financial results across reporting periods and between different companies.
In an M&A transaction, buyers rely heavily on historical financial information when evaluating earnings and determining value. They also use financial statements to analyze working capital, capital expenditures, debt, margins, and other operating trends. However, many privately held lower middle market companies do not maintain financial statements prepared strictly under GAAP. Instead, some companies use cash-basis, tax-basis, or modified accounting methods that satisfy their historical reporting needs.
A lack of GAAP financial statements does not necessarily prevent a successful transaction. Still, buyers must understand the company’s accounting policies and identify significant differences from GAAP. For example, cash-basis statements may not properly match revenues with related expenses during the same accounting period. Likewise, certain liabilities or accrued expenses may not appear on internally prepared financial statements.
These differences may become particularly important when calculating normalized EBITDA and establishing a working capital target. Buyers may propose adjustments when historical accounting practices do not accurately reflect the economics of the business. Beyond that, financial reporting quality may influence a buyer’s perception of risk. Accurate monthly financial statements and reconciled balance sheets will increase confidence in the reported results.
Conversely, inconsistent reporting may raise questions about earnings quality and management’s financial controls. Buyers may then require additional diligence before relying on the company’s historical performance.
GAAP financial statements in M&A also become important when negotiating representations and warranties within the purchase agreement. Sellers must understand exactly what they represent regarding the accuracy and preparation of their financial statements. For this reason, business owners should address financial reporting issues well before beginning a sale process. A knowledgeable CPA will identify accounting inconsistencies, strengthen reporting procedures, and prepare the company for financial due diligence.
An experienced M&A advisor will then help translate the company’s financial performance into information prospective buyers can evaluate. Strong financial reporting reduces uncertainty, supports credible earnings analysis, and helps create a more efficient transaction process.